
If you are reading this guide, there is a very good chance that you or someone close to you, has suffered a leg injury. You may be dealing with pain, heading to constant doctor appointments, missing time from work, and watching medical bills stack up. On top of that, you are likely wondering whether you should file an insurance claim and how much money is actually reasonable to accept as a settlement.
Dealing with insurance adjusters while trying to heal physically can feel overwhelming. This guide breaks down the personal injury process into simple steps so you can understand what your claim might be worth, how insurance payouts work, and how to protect your rights along the way.
Quick Answer: How Much Should You Settle for a Leg Injury?
There is no single “average” settlement amount for a leg injury because no two accidents or recoveries are identical. A minor soft-tissue sprain or mild strain that resolves in a few weeks might settle for a few thousand dollars. On the other hand, a severe fracture requiring surgery, metal hardware, or extended rehab can result in a settlement worth tens or even hundreds of thousands of dollars. Catastrophic injuries causing long-term disability or loss of a limb can lead to much higher payouts.
In general, a fair settlement offer accounts for:
- Medical Bills: Everything from the initial ER visit to future physical therapy.
- Lost Wages: Income you missed out on while recovering, plus any reduction in your future earning ability.
- Injury Severity: How complex the injury is, recovery time, and whether you face permanent physical limits.
- Pain & Suffering: Compensation for your physical discomfort and emotional stress.
- Fault Rules: Whether someone else was entirely responsible or if shared fault applies under your state’s laws.
- Policy Limits: The maximum payout available under the involved insurance policies.
Rather than looking for a single magical number, calculating your claim value comes down to adding up your real financial losses and weighing the personal toll the injury has taken on your daily life.
Step 1: Focus on Health & Medical Documentation
Before worrying about settlement figures, your health and safety must come first. What you do right after an accident sets the stage for both your physical recovery and your financial claim.
- Get Emergency Care: Seek immediate evaluation at an ER or urgent care center. Some leg issues like deep tissue tears or hairline fractures aren’t always obvious right away.
- Follow Your Treatment Plan: Attend all scheduled doctor appointments, physical therapy sessions, and specialist visits. If you skip care, insurance companies may claim your injury wasn’t actually serious.
- Keep an Organized Paperwork Folder: Keep track of hospital bills, diagnostic records (X-rays, MRIs), doctor notes, pay stubs for missed workdays, and receipts for travel to appointments.
Step 2: Understand How Your Leg Injury Severity Drives Value
“Leg injury” covers a huge spectrum of medical diagnoses. Insurance adjusters evaluate settlement amounts based heavily on objective medical records, required surgeries, and how much the injury impacts your daily life.
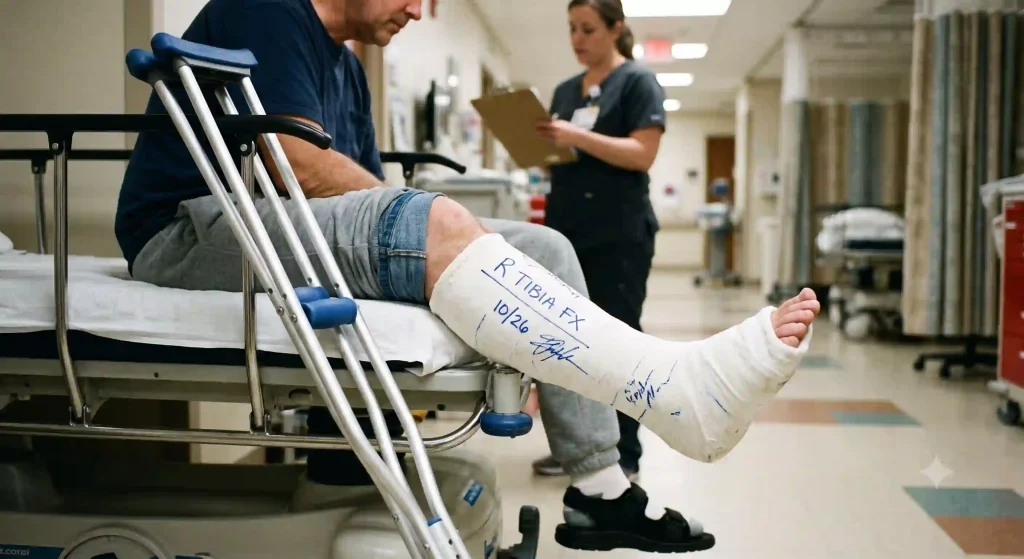
Here is how common leg injuries generally impact claim value:
- Soft-Tissue Injuries & Sprains: Contusions, ankle sprains, or muscle strains usually heal within weeks or months. Settlement values stay on the lower side because medical costs are relatively minimal and long-term effects are rare.
- Ligament & Tendon Tears: An ACL tear in the knee or an Achilles tendon rupture often requires surgical repair and months of rehabilitation. These claims carry higher value due to surgical bills and risk of future joint issues.
- Simple Fractures: A clean broken bone immobilized in a cast involves several weeks of non-weight-bearing recovery, temporary lost wages, and physical therapy.
- Complex Fractures & Surgeries: Broken bones requiring Open Reduction and Internal Fixation (ORIF) where surgeons install plates, screws, or rods carry significantly higher value due to intense recovery, permanent hardware, and potential complications.
- Catastrophic Leg Injuries: Severe crush injuries, nerve damage, compartment syndrome, or amputations drastically increase settlement value due to long-term medical needs, prosthetic costs, and permanent loss of earning capacity.
Different leg injuries create vastly different recovery timelines and financial costs. To see how leg trauma compares to other types of physical accident claims, you can explore our complete guide on injuries and compensation settlements to learn more about claim categories and value factors.
Step 3: What Financial Losses Are Included in Your Claim?
Personal injury compensation breaks down into two primary buckets: Economic Damages (your tangible financial bills) and Non-Economic Damages (the human, non-monetary impact).
Total Settlement Value = Economic Damages (Bills + Lost Wages) + Non-Economic Damages (Pain & Suffering)
1. Economic Damages
These represent every out-of-pocket dollar you lose because of the injury:
- Past and future doctor bills, surgeries, and prescriptions.
- Physical therapy, rehabilitation, and medical equipment (crutches, braces, wheelchairs).
- Past lost wages: Income lost from missed work shifts. According to official Bureau of Labor Statistics occupational injury data, severe lower extremity injuries often result in extended missed work with leg fractures causing a median of 30 to 45 days away from the job.
- Loss of future earning capacity: If your leg injury forces you to take a lower-paying job or retire early.
2. Non-Economic Damages
These address how the injury has affected your quality of life:
- Physical pain and ongoing discomfort.
- Emotional distress, anxiety, or sleep trouble caused by trauma.
- Loss of enjoyment of life (being unable to play sports, exercise, or keep up with your kids).
- Permanent scarring or physical disfigurement.
Step 4: Estimate Your Potential Settlement Value
Understanding how economic losses and pain combine gives you a grounded baseline when negotiating. Adjusters often look at direct financial costs and apply an informal multiplier (ranging from $1.5\times$ to $5\times$ or more depending on severity) to estimate pain and suffering.
To see how these elements come together for your specific situation, try our online personal injury settlement calculator to get an educational baseline estimate of your potential claim.
Note: An online calculator provides an educational starting point, but it cannot guarantee an exact payout or replace a personalized professional legal review.
Step 5: How Insurance Companies Evaluate Offers
Insurance companies are profit-focused businesses. When an adjuster reviews your leg injury claim, their goal is to resolve it for as little as reasonably possible.
- Reviewing Claims & Records: The adjuster reviews police reports, verifies policy terms, and audits medical bills to ensure your treatment directly relates to the accident.
- Software Valuation: Many top carriers run your medical codes through software programs (like Colossus) to spit out a automated settlement range.
- Low Initial Settlement Offers: Insurance adjusters frequently make low opening offers early in the process sometimes before you have finished medical care. They hope you accept a quick payout before realizing the full cost of your future medical needs.
Step 6: Should You Accept an Offer Now or Wait?
Timing is everything when settling an injury claim. Accepting money too quickly can leave you stuck paying for unexpected bills out of your own pocket later on.
Wait for Maximum Medical Improvement (MMI)
Maximum Medical Improvement (MMI) is the point where your doctor determines your leg injury has healed as much as it realistically will.
- If you settle before MMI: You might underestimate future physical therapy costs or miss permanent mobility issues that develop later.
- If you wait until MMI: Your medical records will reflect a clear diagnosis, true treatment costs, and official doctor notes regarding any permanent limits.
Don’t Forget Legal Deadlines
While waiting for MMI is smart, you must keep an eye on the calendar. Every state enforces a strict statute of limitations that sets a firm deadline for filing a lawsuit. If that legal clock runs out before you settle or file court papers, you lose your right to collect compensation. Learn more about state deadlines in our guide on the statute of limitations for personal injury.
Important Issues That Can Reduce Your Payout
Several real-world factors can lower the total amount you receive in a settlement:
- Shared Fault Rules: If you contributed to the accident, state comparative fault rules come into play. For example, under modified comparative fault rules in states like Texas (Tex. Civ. Prac. & Rem. Code § 33.001) or Florida (Fla. Stat. § 768.81), your payout is reduced by your percentage of fault (and barred completely if you are more than 50% or 51% responsible).
- Policy Limits: An insurance policy caps the maximum money an insurer must pay. If the at-fault party has a basic $25,000 policy limit, an insurer will not pay $100,000 regardless of how serious your leg fracture is, unless you have supplemental Uninsured/Underinsured Motorist (UM/UIM) coverage on your own policy.
- Pre-Existing Conditions: Prior knee or leg issues won’t disqualify your claim, but you must prove through medical records that this specific accident worsened your condition beyond its original state.
- Medical Liens: Health insurance plans, Medicare, or hospitals often hold legal rights to be repaid (medical liens) out of your settlement proceeds for treatment costs they paid upfront.
When Should You Talk to a Personal Injury Lawyer?
Minor injuries with quick recoveries, small medical bills, and undisputed fault can often be handled directly with an adjuster. However, seeking professional legal advice is a wise move if:
- Your leg injury required surgery, casting, hardware installation, or joint replacement.
- You are facing permanent mobility limits, limp, or long-term workplace restrictions.
- The insurance company claims you were at fault for the accident.
- Multiple insurance companies or complex commercial policies are involved.
If you are unsure how to evaluate an offer or choose legal representation, take a look at our helpful guide on how to find a good personal injury lawyer to ensure you partner with an experienced attorney who fits your needs.
What Legal Experts Say: How Injury Severity Drives Case Value
When personal injury attorneys evaluate severe leg and lower-extremity injuries, they look closely at two critical factors: the need for surgical intervention and the available insurance policy limits.
According to personal injury attorney breakdowns, such as insights shared by Turzi Law Group, the presence of surgery or permanent mobility loss drastically changes how insurance adjusters and legal teams value a claim. When an injury requires surgical procedures such as installing plates, screws, or pins case values often move into six-figure territory due to steep medical costs and proven physical trauma.
However, legal experts repeatedly emphasize that your actual financial recovery is ultimately capped by available insurance policy limits. In catastrophic cases involving lower-leg amputations or permanent disability, damages may easily reach seven figures, but an insurance company will not pay beyond the policy limit regardless of injury severity. For this reason, identifying every available insurance policy—including your own uninsured/underinsured motorist coverage is a critical step in the claims process.
Frequently Asked Questions (FAQs)
What is a fair settlement for a broken leg?
Settlements vary widely based on whether the fracture was simple or complex, required surgery (ORIF), caused lost work time, or left permanent physical limitations. Simple casted fractures generally settle on the lower end, while surgical fractures command much higher sums due to steep medical costs and pain.
How do I know if a settlement offer is too low?
An offer is likely too low if it fails to pay off 100% of your current medical bills, skips past lost wages, ignores projected future physical therapy, or provides little compensation for physical pain and disruption to your daily life.
Does having leg surgery increase my settlement?
Yes. Leg injuries requiring surgery involve higher medical expenses, longer recovery periods, increased physical pain, and a higher likelihood of long-term joint complications, all of which raise both economic and non-economic damages.
Can I get compensation for future medical treatment?
Yes. If your doctor confirms in your medical records that you will need future physical therapy, hardware removal, or future knee/hip care, those estimated costs can be included in your settlement demand.
What if I injured the same leg in the past?
You can still recover compensation. The law requires the at-fault party to pay for any aggravation or worsening of a pre-existing condition caused by the new accident. Clear pre- and post-accident medical records are key.
How long does a leg injury settlement take?
Simple claims with complete medical healing can resolve in three to six months. Claims involving complex fractures, surgeries, extended physical therapy, or disputed fault can take 12 to 24 months or longer.
Should I settle before finishing physical therapy?
Usually no. Settling before finishing physical therapy or reaching Maximum Medical Improvement (MMI) puts you at risk of underestimating your true medical costs. Once you sign a settlement release, you cannot ask for more money later.
What if I was injured on the job?
Workplace leg injuries typically fall under Workers’ Compensation, which covers medical bills and partial lost wages regardless of fault. However, standard workers’ comp does not pay for pain and suffering unless a third party (not your employer) caused the accident.
Final Thoughts
Deciding how much to settle for a leg injury comes down to understanding your complete medical recovery from the initial emergency visit to your future mobility needs. A fair settlement isn’t just a quick check; it must account for your unpaid medical bills, lost paychecks, and the personal pain you have endured.
Take your time to understand your medical prognosis, reach Maximum Medical Improvement whenever practical, organize your evidence, and evaluate insurance offers with care. To get started, try using our injury settlement calculator for an initial estimate, and consider reaching out to a professional if your injury involves surgery or long-term complications.